Roof Insurance in Newcastle, OK
Understand the covered roof scope, deductible and payment terms before treating an insurance payment as the whole roofing budget. The policy and actual loss control the answer.
- Free roof inspections
- Repair and replacement options explained
- Homes, outbuildings and commercial properties
Call about your roof (405) 561-6780
Roof Insurance before you decide
The roof still needs the right repair whether insurance pays all, part or none of the work. A useful insurance explanation keeps the loss question, the roofing scope and the owner’s share visible.
This guide explains the common payment terms without deciding coverage. The policy, endorsements and the insurer’s handling of the actual loss determine the claim.
- The useful distinction
- Read the actual roof scope and the conditions that change the answer.
- A comfortable next step
- Use the guidance here, then call or request a free inspection about your property.
Roof insurance payments and your share
Actual cash value and replacement cost describe different settlement approaches. The Oklahoma Insurance Department explains that roof terms can differ by policy, so the actual roof endorsement matters.
| Term | What it changes |
|---|---|
| Deductible | What it changesThe portion of a covered loss you are responsible for under the policy. A wind or hail deductible can have its own terms. |
| Actual cash value (ACV) | What it changesA depreciated settlement basis that accounts for factors such as age and condition. It can leave a gap between payment and the cost of new work. |
| Replacement cost | What it changesCoverage can include additional payment after the policy’s repair or replacement conditions are met. Recoverable depreciation, deadlines and documentation follow the actual policy. |
| Uncovered work and upgrades | What it changesItems outside the covered scope or elected upgrades remain separate parts of the project budget. |
Source: Oklahoma Insurance Department homeowners FAQs. General explanation checked October 27, 2026; actual policy terms control.
From storm damage to a covered scope
A roof finding, event date, repair scope and coverage decision answer different questions. Keeping them separate prevents one document from seeming to decide all four.
Roof condition
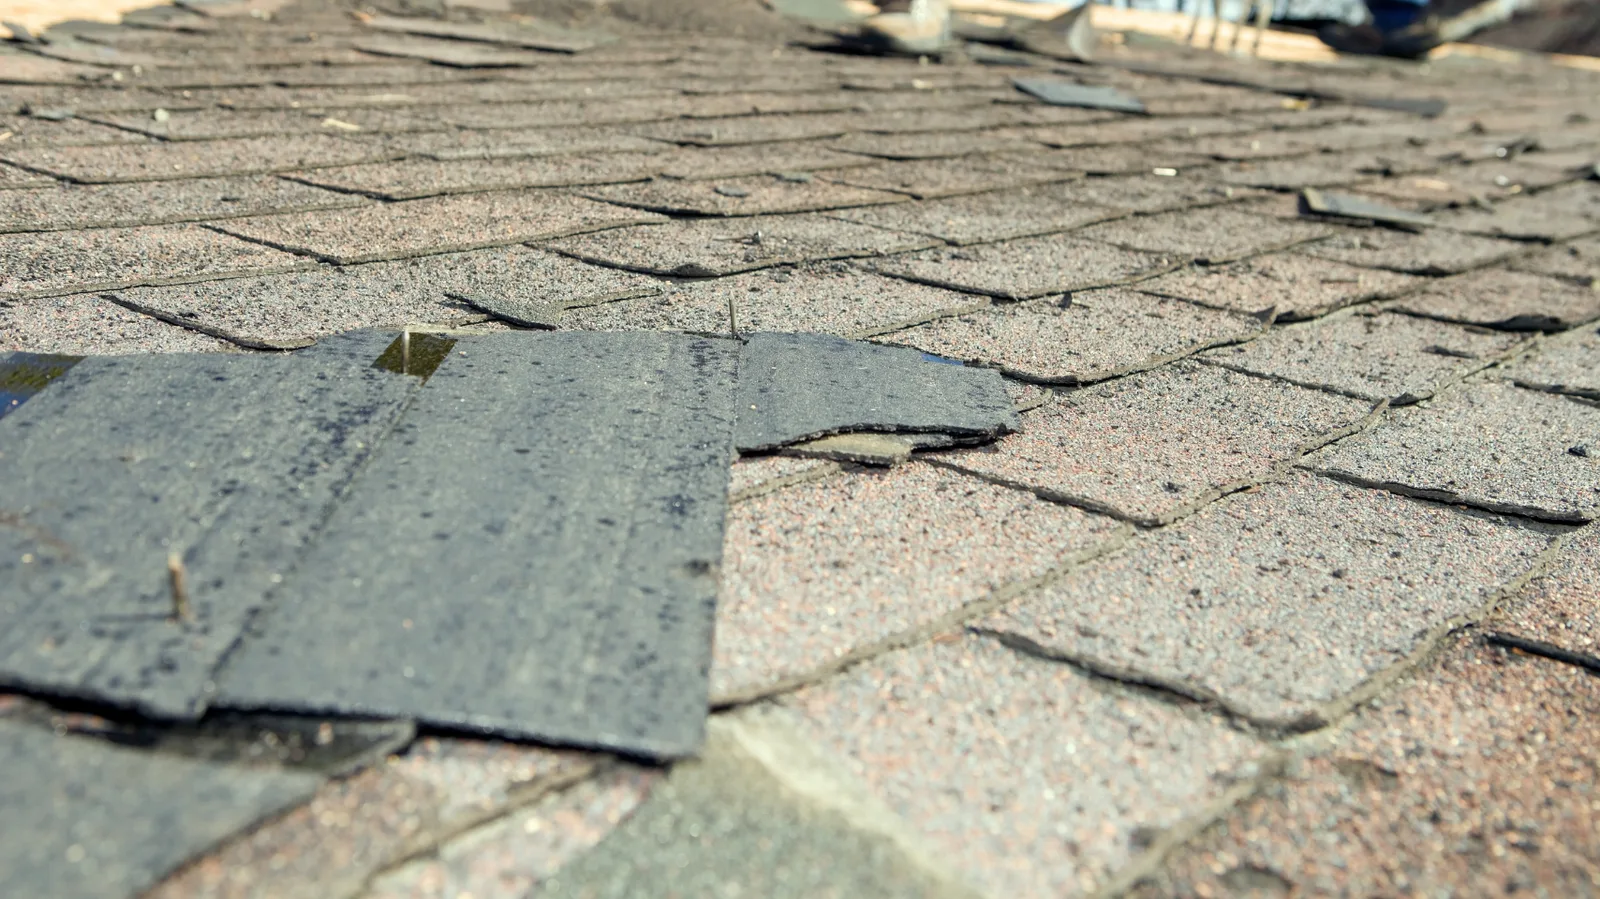
An inspection checks the covering and its connections. Present damage, normal wear and unrelated defects need to be distinguished rather than assigning every mark to the latest storm.
Loss evidence
Property history and actual weather evidence help place the concern in time. A report near Newcastle is context and does not prove damage at the property.
Coverage decision
The insurer applies policy terms to the loss and covered repair scope. A repair estimate above a deductible does not by itself establish coverage or determine the claim outcome.
Repair work and insurance deadlines
If damage leaves the roof exposed, reasonable steps to limit additional loss are a separate concern from waiting for the final claim answer. Keep away from unsafe areas and call about active water entry. The repair plan still needs the cause and affected layers established.
Report a loss promptly according to your policy and insurer’s instructions. Timing for notice, inspection, repairs and any additional payment depends on the actual terms. The Oklahoma Insurance Department’s disaster guidance gives a public starting point; the insurer can explain the requirements on the specific claim.
Roof insurance FAQs
Does insurance replace a roof because it is old?
A roof’s age alone is not a covered event. Coverage depends on the policy, cause of loss, exclusions and settlement terms. Wear and a storm-related loss are different questions.
Is replacement cost always one payment?
Not necessarily. Policies can pay an initial depreciated amount and additional recoverable depreciation after required conditions are met. Deadlines and payment conditions follow the actual policy.
Can an inspection guarantee a claim approval?
No. The inspection establishes roof condition. The insurer decides coverage under the policy and loss evidence.
Where can I get Oklahoma insurance help?
The Oklahoma Insurance Department provides public wind and hail guidance and consumer-assistance paths. For a specific claim, the insurer’s policy explanation and required process remain the starting point.
Request a roof inspection in Newcastle
Tell us about the roof concern and any storm date you already have in mind. We can begin with the condition of the actual roof.